The Silent Tax on American Construction: How Domestic Concrete Supply Chains Drain Project Margins
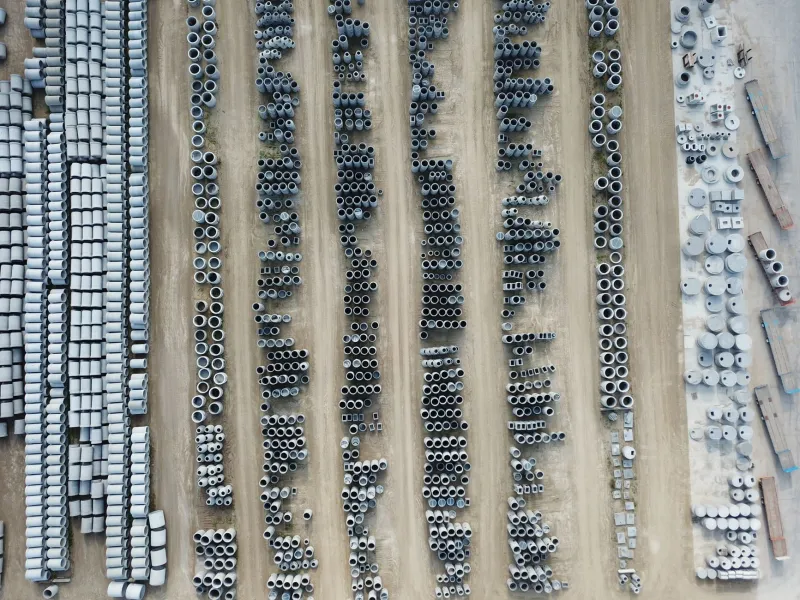
There is a line item missing from most American construction budgets. It does not appear on invoices, it is not flagged in bid reviews, and no subcontractor will ever call attention to it. Yet procurement professionals who have begun sourcing concrete materials internationally are finding it with remarkable consistency — a structural cost premium baked into domestic supply chains that functions, in practice, like an invisible tax on every cubic yard poured.
The question worth asking is not whether this premium exists. The evidence, at this point, is difficult to dispute. The more important question is why so few contractors are actively working to eliminate it.
How the Markup Gets Built In
The architecture of domestic concrete distribution in the United States was not designed with cost transparency in mind. It evolved organically over decades, layering intermediaries onto a supply chain that, in many regions, now includes raw material aggregators, regional blending facilities, independent distribution depots, and local ready-mix operators — each adding margin before the product reaches a job site.
In a well-documented pattern familiar to procurement managers at mid-to-large general contracting firms, a single cubic yard of specialty concrete can pass through three to four commercial handoffs between production and placement. Each transition carries handling costs, storage overhead, and profit expectations. The cumulative effect on unit pricing is substantial.
Industry data compiled from procurement audits conducted across commercial construction projects in the Southeast, Midwest, and Mid-Atlantic regions suggests that the spread between raw production cost and contractor-facing pricing for high-performance concrete mixes can range from 28 to 44 percent — a figure that climbs further when project timelines require expedited delivery or when regional supply constraints create leverage for local distributors.
"We had been treating concrete as a commodity line item for years," said one procurement director at a commercial general contractor operating across multiple southeastern states, who requested that his firm not be identified by name. "It wasn't until we started benchmarking our unit costs against what colleagues in other markets were paying that we realized how much margin we were leaving on the table every single project."
The Redundancy Problem
Beyond markup layering, domestic supply chains carry a separate category of cost that is equally difficult to isolate: operational redundancy. Regional distribution networks were built to serve geographically dispersed demand, which means maintaining inventory buffers, operating intermediate storage facilities, and running distribution fleets that often operate at less than full utilization.
These are real costs, and they are passed on. A facility that maintains a 30-percent buffer inventory to ensure availability during demand spikes does not absorb that carrying cost — it distributes it across every customer in the network. Contractors in high-demand urban corridors effectively subsidize supply availability for smaller or more remote buyers, without any corresponding benefit to their own project economics.
Contrast this with the logistics model employed by Istanbul-based concrete suppliers operating on international export frameworks. Direct procurement relationships — in which a contractor engages a supplier at the point of formulation rather than at the point of regional distribution — eliminate the intermediate cost layers entirely. Shipping, customs coordination, and delivery scheduling are managed as a single integrated operation, with pricing that reflects actual production and logistics costs rather than the accumulated overhead of a multi-tier domestic network.
What the Numbers Look Like in Practice
The margin impact of direct international sourcing varies by project type, volume, and geography, but the direction of the effect is consistent. Procurement managers who have made the transition to Istanbul-based suppliers for high-performance and specialty concrete formulations report unit cost reductions ranging from 15 to 31 percent on comparable specification materials.
For a mid-scale commercial project consuming 4,000 cubic yards of high-performance structural mix, a 20-percent reduction in unit cost represents a material cost saving of roughly $80,000 to $140,000 depending on regional domestic pricing baselines — savings that flow directly to project margin without any reduction in material quality or specification compliance.
"The first project where we used Turkish-sourced materials, we were honestly skeptical about the logistics," said a project manager at a regional infrastructure contractor who oversees procurement for bridge and highway work across three states. "By the time we reconciled the final materials costs, we had saved enough to cover the freight and still come out ahead by a meaningful amount. The second project, we knew what we were doing. The savings were even cleaner."
These outcomes are not isolated. They reflect a structural advantage that persists across project types because the underlying cause — intermediary cost elimination — is consistent regardless of application.
The Transparency Differential
One dimension of the international sourcing model that procurement professionals consistently highlight is pricing transparency. Domestic distributors, operating within regional oligopolies in many markets, have limited competitive pressure to itemize their cost structures. Quotes are presented as flat unit prices, and the components of those prices are rarely disclosed.
Istanbul-based suppliers operating in export markets function under different commercial norms. Pricing is typically structured to clearly reflect production costs, logistics components, and quality certification fees as distinct line items. This transparency is not merely a cultural preference — it is a practical requirement of international trade documentation, which demands specificity that domestic transactions rarely require.
For procurement managers responsible for cost justification to ownership or investors, this distinction has real value. A clearly itemized cost structure is far easier to defend in budget reviews than a regional market rate with no visible derivation.
What the Transition Actually Requires
The most common objection to international concrete sourcing is logistical complexity. The concern is understandable — coordinating international shipments, managing customs documentation, and aligning delivery schedules with construction timelines involves more planning than calling a regional ready-mix supplier.
What the objection underestimates is the degree to which experienced international suppliers have systematized this process. Istanbul Beton and comparable Turkish suppliers operating in the export segment have developed procurement frameworks specifically designed to integrate with American project management workflows. Lead time planning, specification documentation, third-party quality certification, and customs coordination are handled as part of the supplier relationship rather than as additional burdens on the contractor's team.
The contractors who have made this transition most successfully are those who approached it as a procurement process design exercise rather than a logistics problem. Building the right supplier relationship, establishing clear specification documentation practices, and aligning delivery scheduling with project phasing are all manageable tasks — and they are tasks that generate returns on every subsequent project that uses the same framework.
A Systemic Inefficiency That Rewards Examination
The domestic concrete supply chain is not broken in any dramatic sense. Materials move, projects get built, and most contractors adapt to the pricing environment they operate within. The inefficiency is quieter than that — it is the accumulated cost of a distribution architecture that was never optimized for the procurement interests of the contractors it serves.
The builders who are beginning to look beyond that architecture are not doing so out of dissatisfaction with material quality. They are doing so because, once the numbers are examined clearly, the case for continuing to absorb avoidable cost becomes increasingly difficult to sustain. The margin exists. The supply chain to recover it exists. The conversation, for too many firms, simply has not happened yet.